Most people who call us have been carrying the debt for years. They have paid the minimums, taken the collection calls, and watched the balances stay the same. Then something changes. A lawsuit is served, a paycheck comes up short because of a garnishment, a bank account is frozen, or a mortgage lender sends a notice of default.
Bankruptcy is the one tool in the law that stops all of it at once and, in most cases, ends it permanently. It is a federal court process, so the rules are the same whether a creditor is a national bank, a local collection agency, or the IRS. What differs from case to case is the chapter, the timing, and the preparation. That is the work we do.
Attorney Gregory Grigoryants has represented more than a thousand clients in bankruptcy, debt collection defense, and tax matters over thirteen years, and has helped discharge more than $15 million in debt. He handles every case himself, from the first meeting through the discharge order, and he and his staff speak English and Russian.
Is Bankruptcy the Right Move?
Not everyone who calls us should file. Some people are better served by defending a lawsuit, negotiating a settlement, or waiting out the statute of limitations. A first conversation sorts that out. Bankruptcy is usually the right answer when several of these are true:
- You owe more in credit cards, medical bills, and personal loans than you could pay off in a few years even with real sacrifice.
- Your wages are being garnished, a bank account has been levied, or a judgment has been entered against you.
- You are behind on a mortgage or car loan and want to keep the property.
- Collectors are suing or threatening to sue, and the debts are too large or too many to settle one at a time.
- You owe back taxes that are old enough to be discharged, or recent taxes that need to be paid through a plan the IRS cannot refuse.
- You personally guaranteed debts of a business that has closed or is closing.
- You have student loans you will never realistically repay and a genuine hardship behind that fact.
If only one of these fits, there may be a narrower fix. Our debt collection defense practice covers those alternatives, and we handle them too.
What Filing Stops, Immediately
The moment a bankruptcy petition is filed, a federal court order called the automatic stay takes effect. No hearing is needed and no creditor has to agree. Under it, creditors must stop:
- Wage garnishments. The employer must stop withholding as soon as it has notice of the filing.
- Bank levies and the freezing of accounts.
- Collection lawsuits, including ones already set for trial.
- Foreclosure sales, even one scheduled for the next morning.
- Vehicle repossessions, and in many cases a car that was just repossessed must be returned.
- Collection calls, letters, and demands of every kind.
- IRS and Franchise Tax Board collection, including tax levies and new liens.
- Utility shut-offs for past-due balances.
Criminal cases, child and spousal support proceedings, and most license and regulatory matters continue. A creditor can also ask the court to lift the stay for a specific asset, most often a house or car the debtor is not paying for. Those motions are predictable and are part of the planning in Stage 2.
Chapter 7, Chapter 13, or Chapter 11: Which One Fits
Three chapters cover nearly every individual and small business case. Choosing between them is the single most important decision in the case, and it depends on your income, what you own, what you owe, and what you want to keep.
| Chapter 7 | Chapter 13 | Chapter 11, Subchapter V | |
|---|---|---|---|
| Best for | Individuals and couples whose income is at or below the California median, or whose debts are mostly business or tax debt, and whose property is protected by the exemptions | Homeowners behind on a mortgage, people with income above the Chapter 7 limit, and anyone with property the exemptions do not fully cover | Small businesses and their owners who need to restructure debt and keep operating |
| What happens to the debt | Unsecured debt is wiped out by a discharge order | Debts are paid in part through a three- to five-year plan; the balance is discharged at the end | Debts are restructured under a plan the court confirms, often paying creditors a fraction over three to five years |
| Your property | Kept, as long as it is covered by the exemptions. Most clients keep everything | Kept. Non-exempt value is paid through the plan instead of surrendered | Kept. The business continues under the owner’s control |
| Length | About three to four months | Three to five years | Plan typically confirmed within a few months; payments run three to five years |
| Court filing fee | $338 | $313 | $1,738 |
| Our guide | How Chapter 7 works | How Chapter 13 works | Subchapter V for small business |
Two cases that look alike on paper can call for different chapters. A family with a modest income but $150,000 of equity in a home may need Chapter 13 to protect the house. A business owner with high income but mostly business debt may qualify for Chapter 7 because the means test does not apply to non-consumer debt. We run both analyses before recommending anything.
The Consultation
A clear answer about where you stand, before you commit to anything.
The first meeting is a working session, in person at either office or by phone or video. We go through your income, what you own, what you owe, and what has already happened: lawsuits, garnishments, levies, notices of default. By the end you will know whether bankruptcy fits, which chapter, what it would protect, what it would cost, and what the alternative would be if you do nothing or choose another route.
If bankruptcy is not the right tool, we say so. A meaningful share of the people we meet leave with a different plan, such as defending the lawsuit or negotiating a settlement.
- Pay stubs or other proof of income for the last seven months
- Your last two years of tax returns
- Recent bank statements
- Any lawsuit papers, garnishment orders, or collection letters
- Mortgage and car loan statements, if you have them
Planning
Choosing the chapter and the filing date, and making sure your property is protected before the petition is filed.
Timing matters more than most people expect. Filing before a tax refund arrives, right after a bonus, or too soon after a large payment to a relative can cost you money or draw scrutiny from the trustee. Filing too late can mean a garnishment already took the paycheck. We set the date deliberately.
The exemption analysis is done here too. California gives you a choice between two sets of exemptions, and the right set depends on whether home equity, a vehicle, retirement accounts, or cash is the asset most in need of protection. That choice is discussed under Your Property below.
Finally, the required pre-filing credit counseling course is completed online. It takes about an hour and we point you to an approved provider.
Filing
Putting a complete and accurate petition in front of the court, and stopping collection the same day.
The petition is a set of schedules that lists every debt, every asset, your income and expenses, and your recent financial history, all signed under penalty of perjury. Accuracy is what earns the discharge, so we prepare the schedules ourselves from your documents and review every page with you before anything is signed.
Cases are filed electronically with the United States Bankruptcy Court for the Central District of California. The automatic stay takes effect at that moment. If a garnishment is running, we notify the employer and the levying officer directly rather than waiting for the court’s mailed notice, so the next paycheck is whole.
The Meeting of Creditors
A short appearance before the trustee, with us beside you.
About a month after filing, the trustee assigned to the case holds a meeting of creditors, also called the 341 meeting. Despite the name, creditors rarely attend. The trustee confirms your identity, asks whether the schedules are accurate, and asks a handful of questions about your property and finances. Most meetings last under ten minutes and are held by video.
We prepare you for the questions beforehand and attend the meeting with you. In a Chapter 13 or Chapter 11 case, this stage also includes the trustee’s review of the plan and, if needed, negotiation over its terms before the confirmation hearing.
Discharge
The court order that ends the debt, and what comes after it.
In a Chapter 7 case the discharge order usually arrives about sixty days after the meeting of creditors, roughly three to four months from filing. In Chapter 13 it comes at the end of the plan. The order permanently bars every discharged creditor from ever trying to collect again. A creditor who does can be held in contempt.
Credit cards, medical bills, personal loans, deficiency balances after a repossession or foreclosure, old utility and phone bills, most judgments, business debts you guaranteed, and income taxes that meet the age tests. Student loans can be discharged when repayment would impose an undue hardship, which is a separate proceeding we handle regularly.
Some debts survive: child and spousal support, recent income taxes, most student loans unless hardship is proven, debts from fraud or drunk driving injuries, and criminal fines. A secured loan you want to keep paying, such as a car loan, continues under a reaffirmation agreement or by simply keeping the payments current.
Credit recovers faster than most clients expect. With the debt gone and no new defaults, many clients qualify for a car loan within a year and a mortgage within two to four years.
Your Property: What You Keep
The fear of losing the house, the car, or the retirement account keeps many people from calling until it is too late. In practice, the great majority of our Chapter 7 clients keep everything they own, and every Chapter 13 and Chapter 11 client does.
California law protects property through exemptions. You choose one of two systems, and the right choice depends on what you own:
- The homestead system protects a large amount of equity in your home, several hundred thousand dollars in Los Angeles County, with the figure adjusted each year for inflation. It also protects retirement accounts, a vehicle, household goods, tools of your trade, and a portion of wages.
- The wildcard system gives a smaller homestead but a flexible wildcard amount that can be applied to anything, including cash in the bank, a tax refund, or a second vehicle. It is usually the better choice for renters and for people with savings.
Retirement accounts such as 401(k)s, IRAs, and pensions are protected in full under either system. If something is not covered, it is addressed in planning, not discovered at the meeting of creditors.
Student Loans, Taxes, and Business Debt
Student loans
Student loans are not automatically discharged, but they can be. The test is whether repaying them would impose an undue hardship, and since 2022 the Department of Justice has followed guidelines that make the outcome far more predictable for federal loans. Our student loan guide explains how it works.
Tax debt
Income taxes can be discharged in bankruptcy when the return was due more than three years before filing, was actually filed more than two years before, and the tax was assessed more than 240 days before. Taxes that are too recent to discharge can be paid through a Chapter 13 plan over three to five years, generally without further penalties and interest accruing while the plan runs. Because we also handle tax resolution outside of bankruptcy, we can compare a bankruptcy filing with an offer in compromise or a payment plan and recommend whichever costs less.
Business debt
Owners who personally guaranteed leases, loans, or merchant cash advances for a business that has closed often qualify for Chapter 7 even with high income, because the means test does not apply when most of the debt is business debt. A business that should keep operating is a candidate for Subchapter V, the streamlined small business reorganization. Our guide on closing a business in California covers the wind-down side.
Fees
We charge a flat fee for Chapter 7 and Chapter 13 cases, quoted at the consultation and set out in a written agreement before any work begins. There are no hourly charges and no surprises. Chapter 11 Subchapter V cases are quoted individually after the first meeting, since they vary more in size.
Court filing fees are separate and are paid to the court: $338 for Chapter 7, $313 for Chapter 13, and $1,738 for Chapter 11. The two required credit counseling courses and a credit report add a small amount.
Many employer-sponsored legal plans, including ARAG and MetLife Legal Plans, cover a Chapter 7 or Chapter 13 filing in full. If you have one of these benefits, bring the plan information to the consultation and we will confirm coverage.
Where We Practice
We file in the United States Bankruptcy Court for the Central District of California. Cases from the Westside, Hollywood, Mid-Wilshire, and central Los Angeles are heard at the Los Angeles Division downtown. Cases from the San Fernando Valley are heard at the San Fernando Valley Division in Woodland Hills. Our two offices sit on either side of that line:
- Beverly Hills: 9350 Wilshire Blvd, Suite 203, Beverly Hills, CA 90212, serving Beverly Hills, West Hollywood, Santa Monica, Culver City, Westwood, Brentwood, Hollywood, Mid-Wilshire, Koreatown, and downtown Los Angeles.
- Sherman Oaks: 15303 Ventura Blvd, Suite 900, Sherman Oaks, CA 91403, serving Sherman Oaks, Studio City, Encino, Tarzana, Van Nuys, North Hollywood, Burbank, Glendale, Woodland Hills, and the rest of the San Fernando Valley.
Consultations are also available by phone and video for clients anywhere in Los Angeles County. The attorney and staff speak Russian. Мы говорим по-русски.
Frequently Asked Questions
How much does it cost to file bankruptcy in Los Angeles?
Our attorney fee is a flat fee quoted at the consultation. The court charges $338 to file a Chapter 7 case and $313 for Chapter 13, plus a small amount for the two required courses. Many employer legal plans cover the attorney fee entirely.
How long does a bankruptcy take?
A Chapter 7 case usually takes three to four months from filing to discharge. A Chapter 13 plan runs three to five years, but the protection from creditors starts the day the case is filed.
Will I lose my house or my car?
Almost never. California’s exemptions protect a large amount of home equity, a vehicle, and all retirement accounts. If you are behind on the payments and want to keep the property, Chapter 13 lets you catch up over time. The exemption analysis is done before filing, so there are no surprises.
Do I have to go to court?
There is one required appearance, the meeting of creditors, which is a short session with the trustee rather than a hearing before a judge. It is currently held by video in most cases. We attend with you. Most Chapter 7 clients never see a courtroom.
Can I file without my spouse?
Yes. One spouse can file alone. Household income is still counted for the means test, and community property is part of the case, but the non-filing spouse’s credit is not directly affected. Whether to file jointly is one of the questions we work through at the consultation.
How soon can I file again?
You can receive a Chapter 7 discharge once every eight years, measured from filing date to filing date. A Chapter 13 discharge is available four years after a Chapter 7 and two years after a prior Chapter 13.
Will bankruptcy stop a wage garnishment that has already started?
Yes, immediately. The garnishment must stop as soon as the employer has notice of the filing, and we send that notice ourselves the day the case is filed. Wages taken in the ninety days before filing can sometimes be recovered as well.
Can the IRS still collect after I file?
Not while the case is open. The automatic stay applies to the IRS and the Franchise Tax Board. Income taxes old enough to meet the discharge tests are wiped out; newer ones are paid through a Chapter 13 plan or addressed through a separate tax resolution after the case.
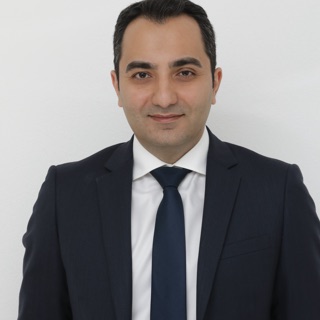
Gregory Grigoryants is a California attorney (State Bar No. 286804) who has represented individuals, families, and business owners in bankruptcy, debt collection defense, and tax resolution matters for more than 13 years. He practices from offices in Sherman Oaks and Beverly Hills and speaks English and Russian.